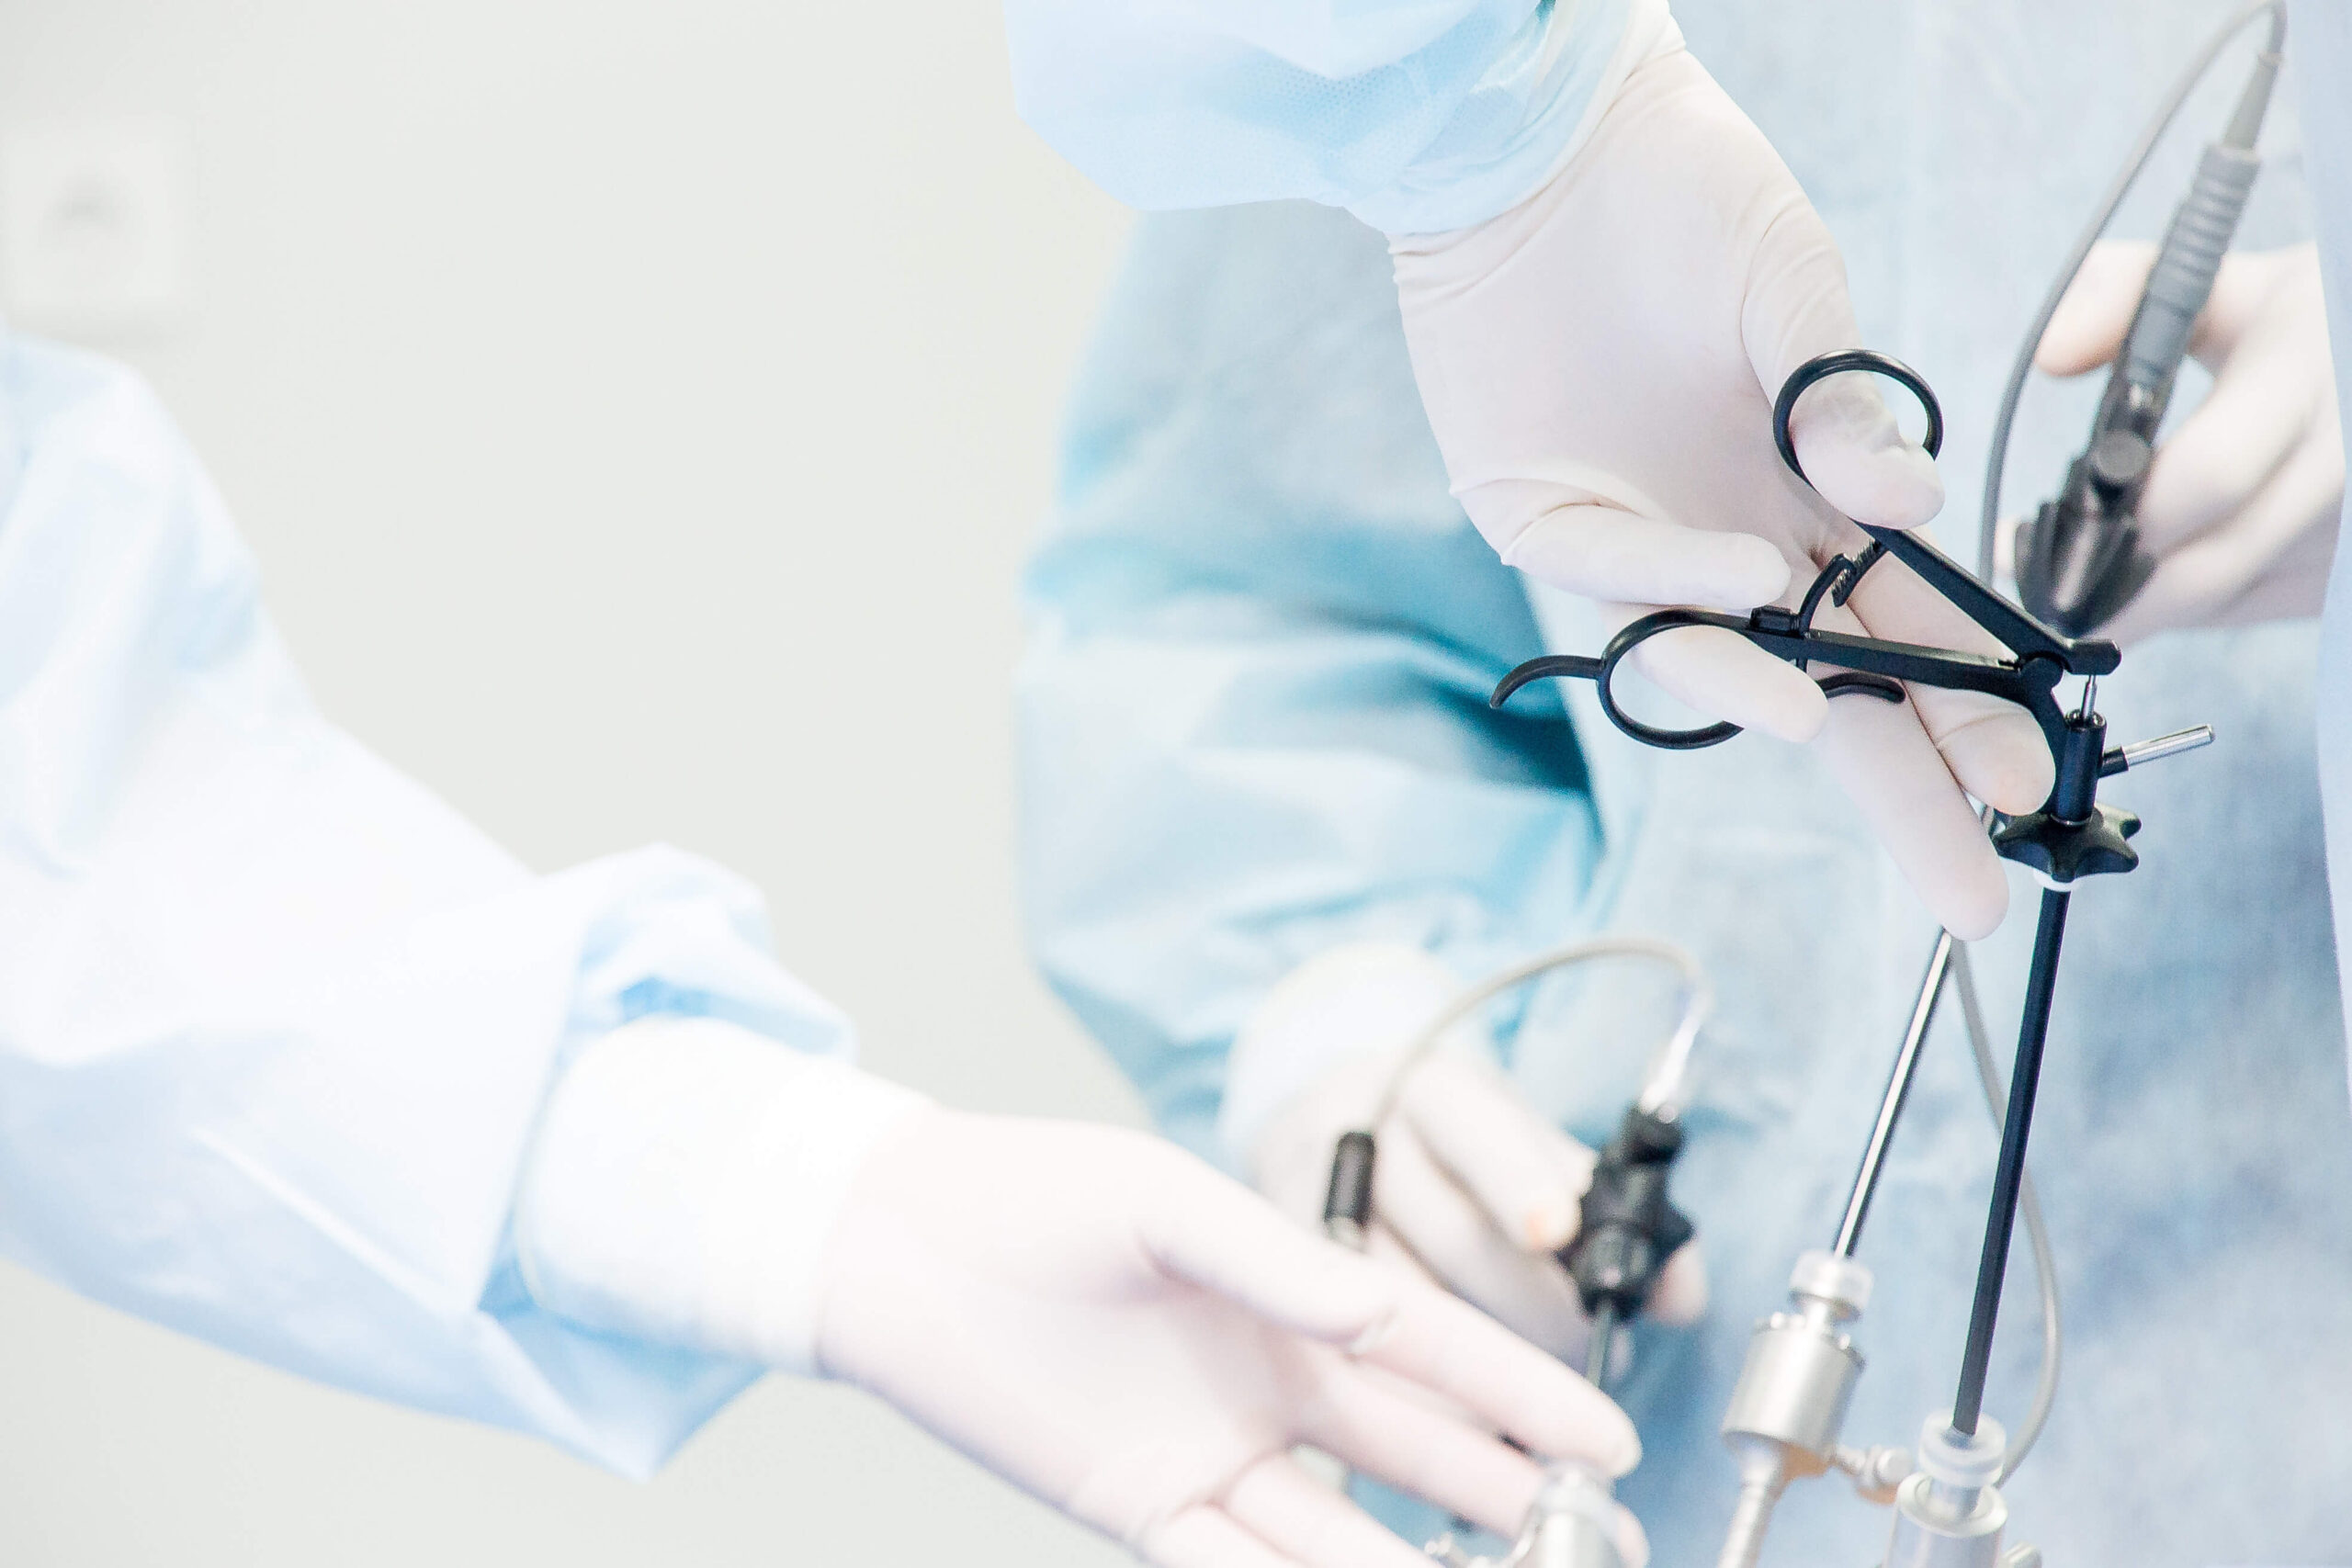
North America currently commands the largest share of this landscape, bolstered by a sophisticated healthcare infrastructure and a high prevalence of conditions requiring surgical intervention, such as obesity and colorectal disorders. Industry analysts point to the increasing adoption of laparoscopic procedures—favored for their clinical benefits like reduced postoperative pain and shorter hospital stays—as the primary engine for demand. Among product categories, laparoscopes remain the dominant segment, while general surgery continues to be the most significant application for these tools.
Market participants are increasingly focused on balancing capital equipment sales with recurring revenue from procedure-specific consumables. Strategies for growth vary: while some firms invest heavily in internal product development, others are expanding their surgical portfolios through targeted acquisitions, such as Microline Surgical’s purchase of liver-retraction assets or Advanced Medical Solutions’ consolidation of Peters Surgical. As the industry evolves, competitive assessment now requires a granular look at product-level revenue rather than broad corporate figures, ensuring that growth metrics accurately reflect the shift toward more specialized surgical technologies.


Comments (0)
No comments yet. Be the first!