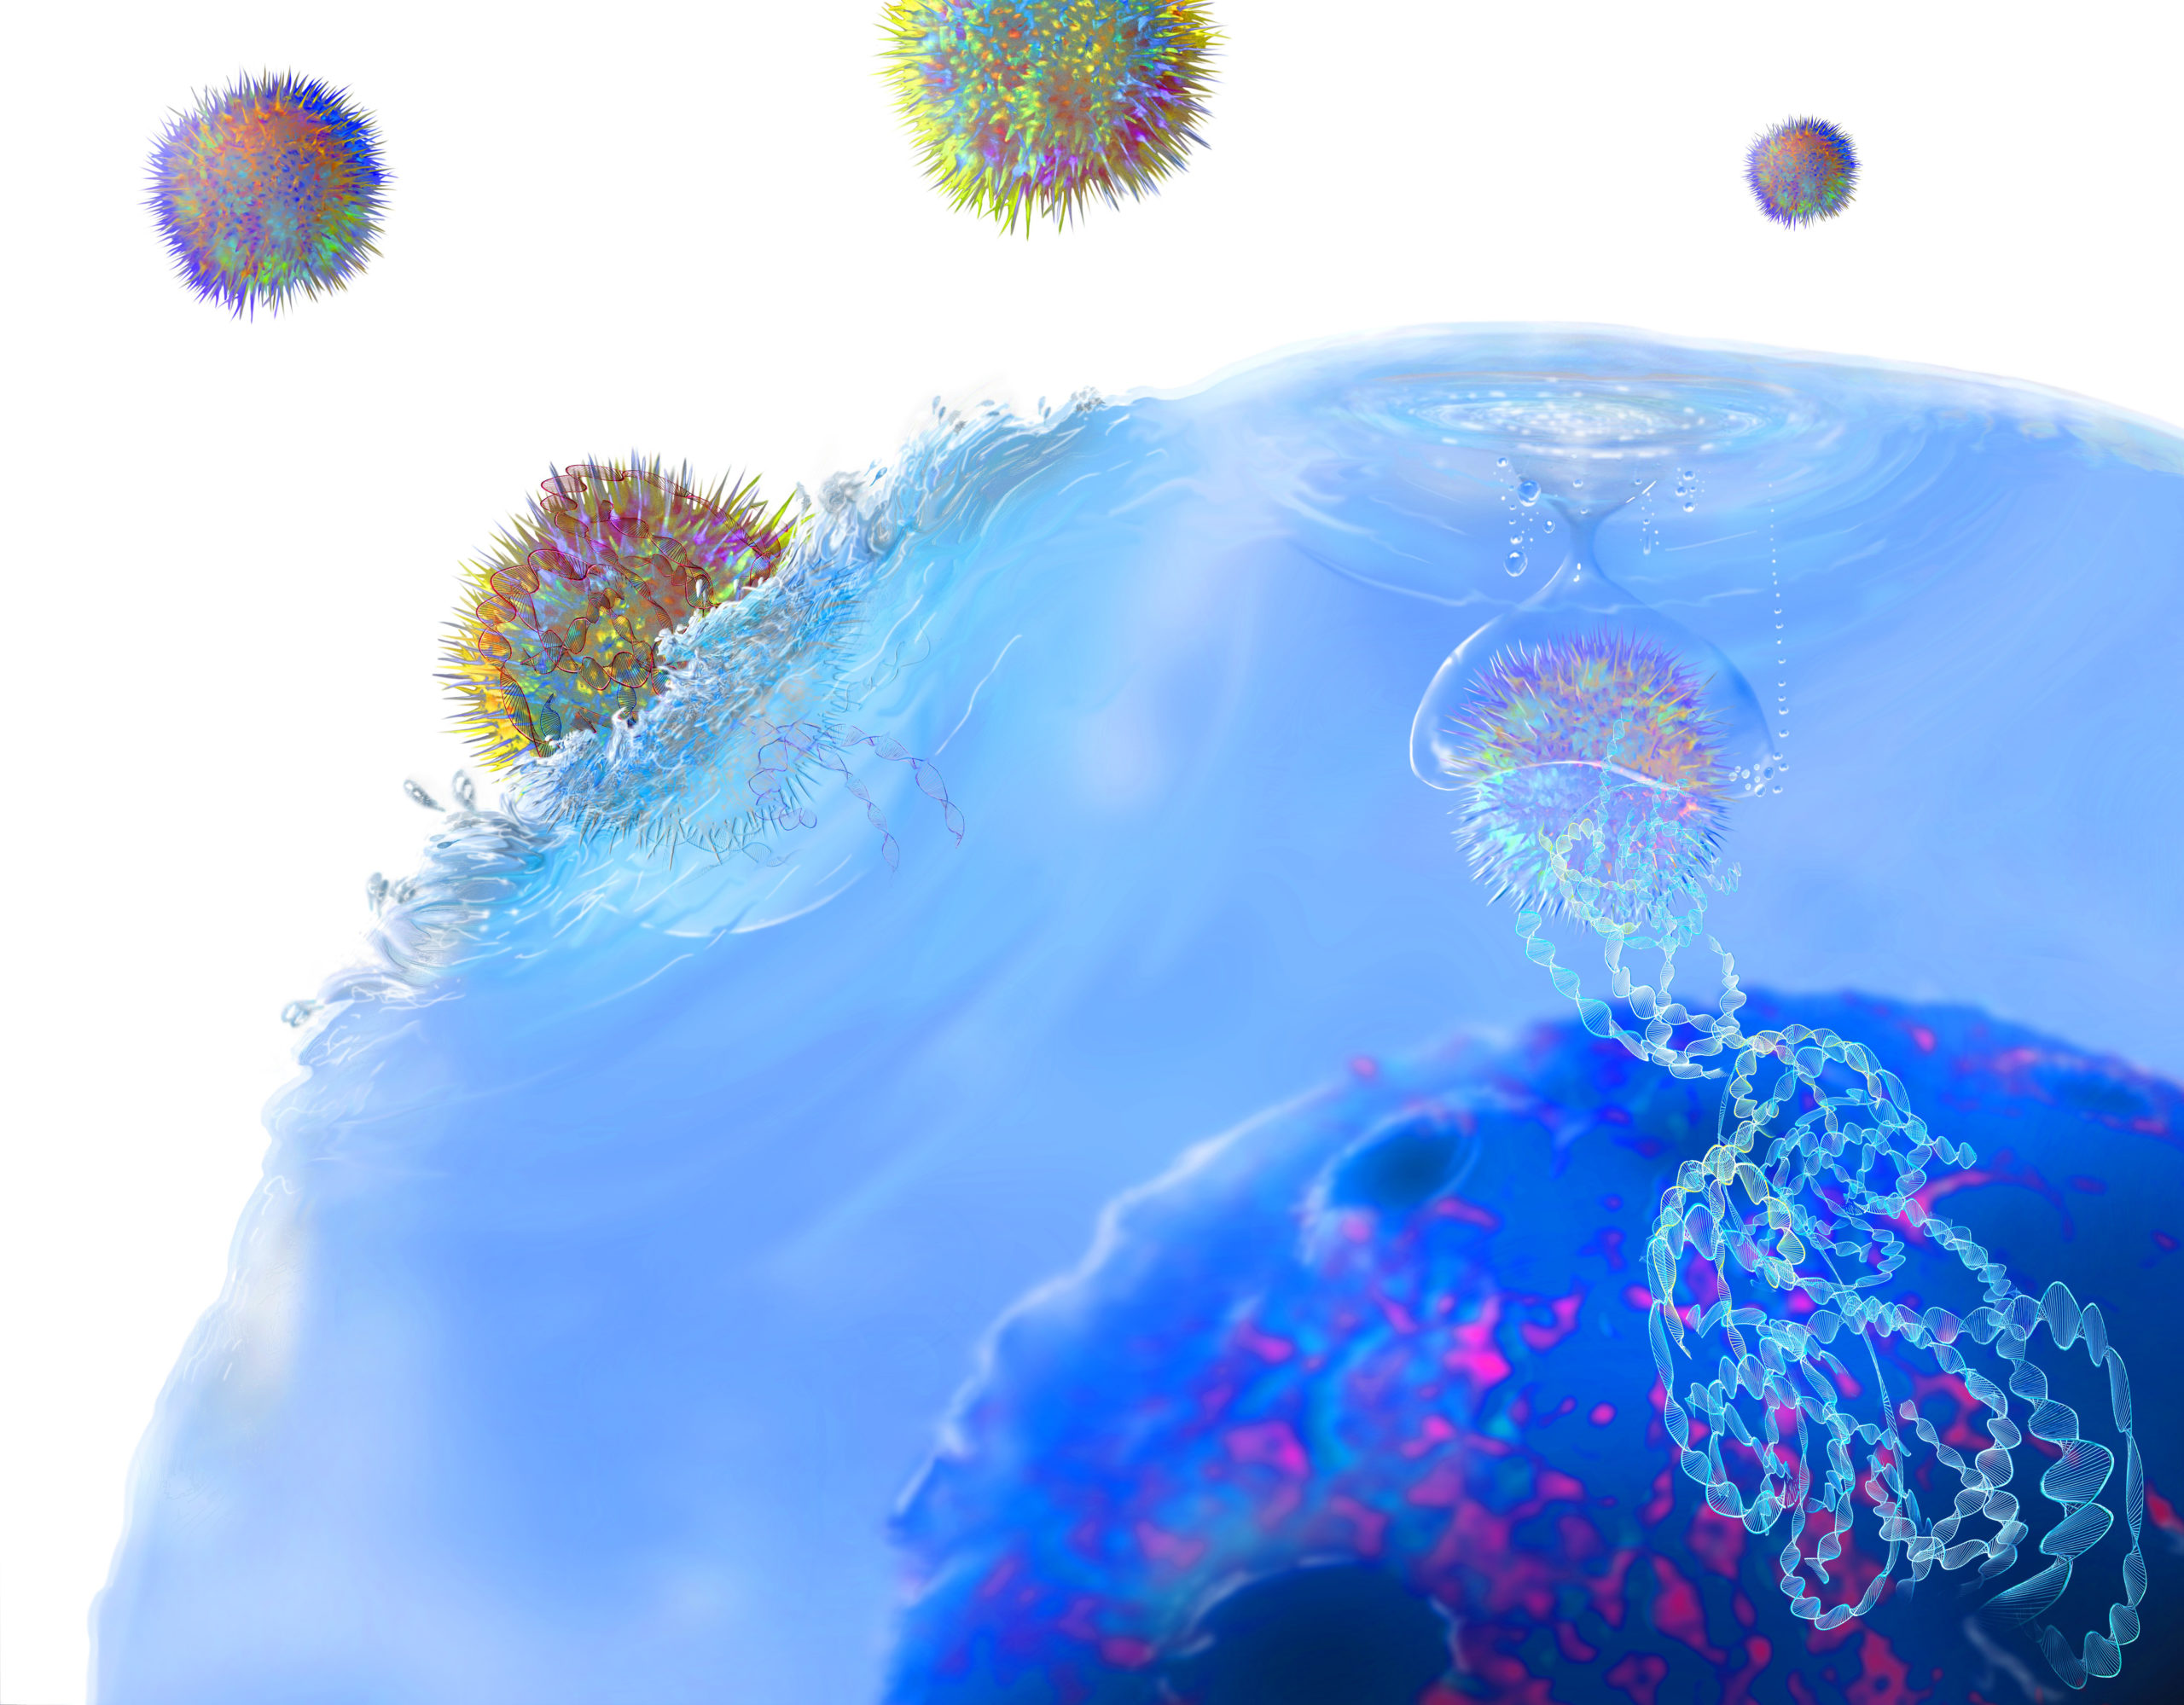
The expansion is driven by the increasing prevalence of patients who develop resistance to PD-1 and PD-L1 inhibitors, which have become standard frontline therapies across various oncology sectors. As these patients progress, the demand for secondary treatment sequences and novel immunologic targets is intensifying. Currently, North America dominates the landscape with a 47% market share, though the Asia Pacific region is expected to lead global growth with a 13.77% annual rate as access to specialized oncology care expands in countries like Japan and South Korea.
Market value is heavily concentrated in hospital pharmacies, which accounted for 78% of revenue in 2025, largely due to the clinical supervision required for complex infusions and emerging cell-based therapies. Non-small cell lung cancer remains the primary application, representing 38% of total revenue. While industry leaders such as Merck, Bristol Myers Squibb, and Roche maintain strong positions, the future of the segment rests on the ability of developers to provide robust clinical evidence for refractory-line efficacy while managing the significant immune-related toxicity profiles that often accompany combination regimens.
Comments (0)
No comments yet. Be the first!