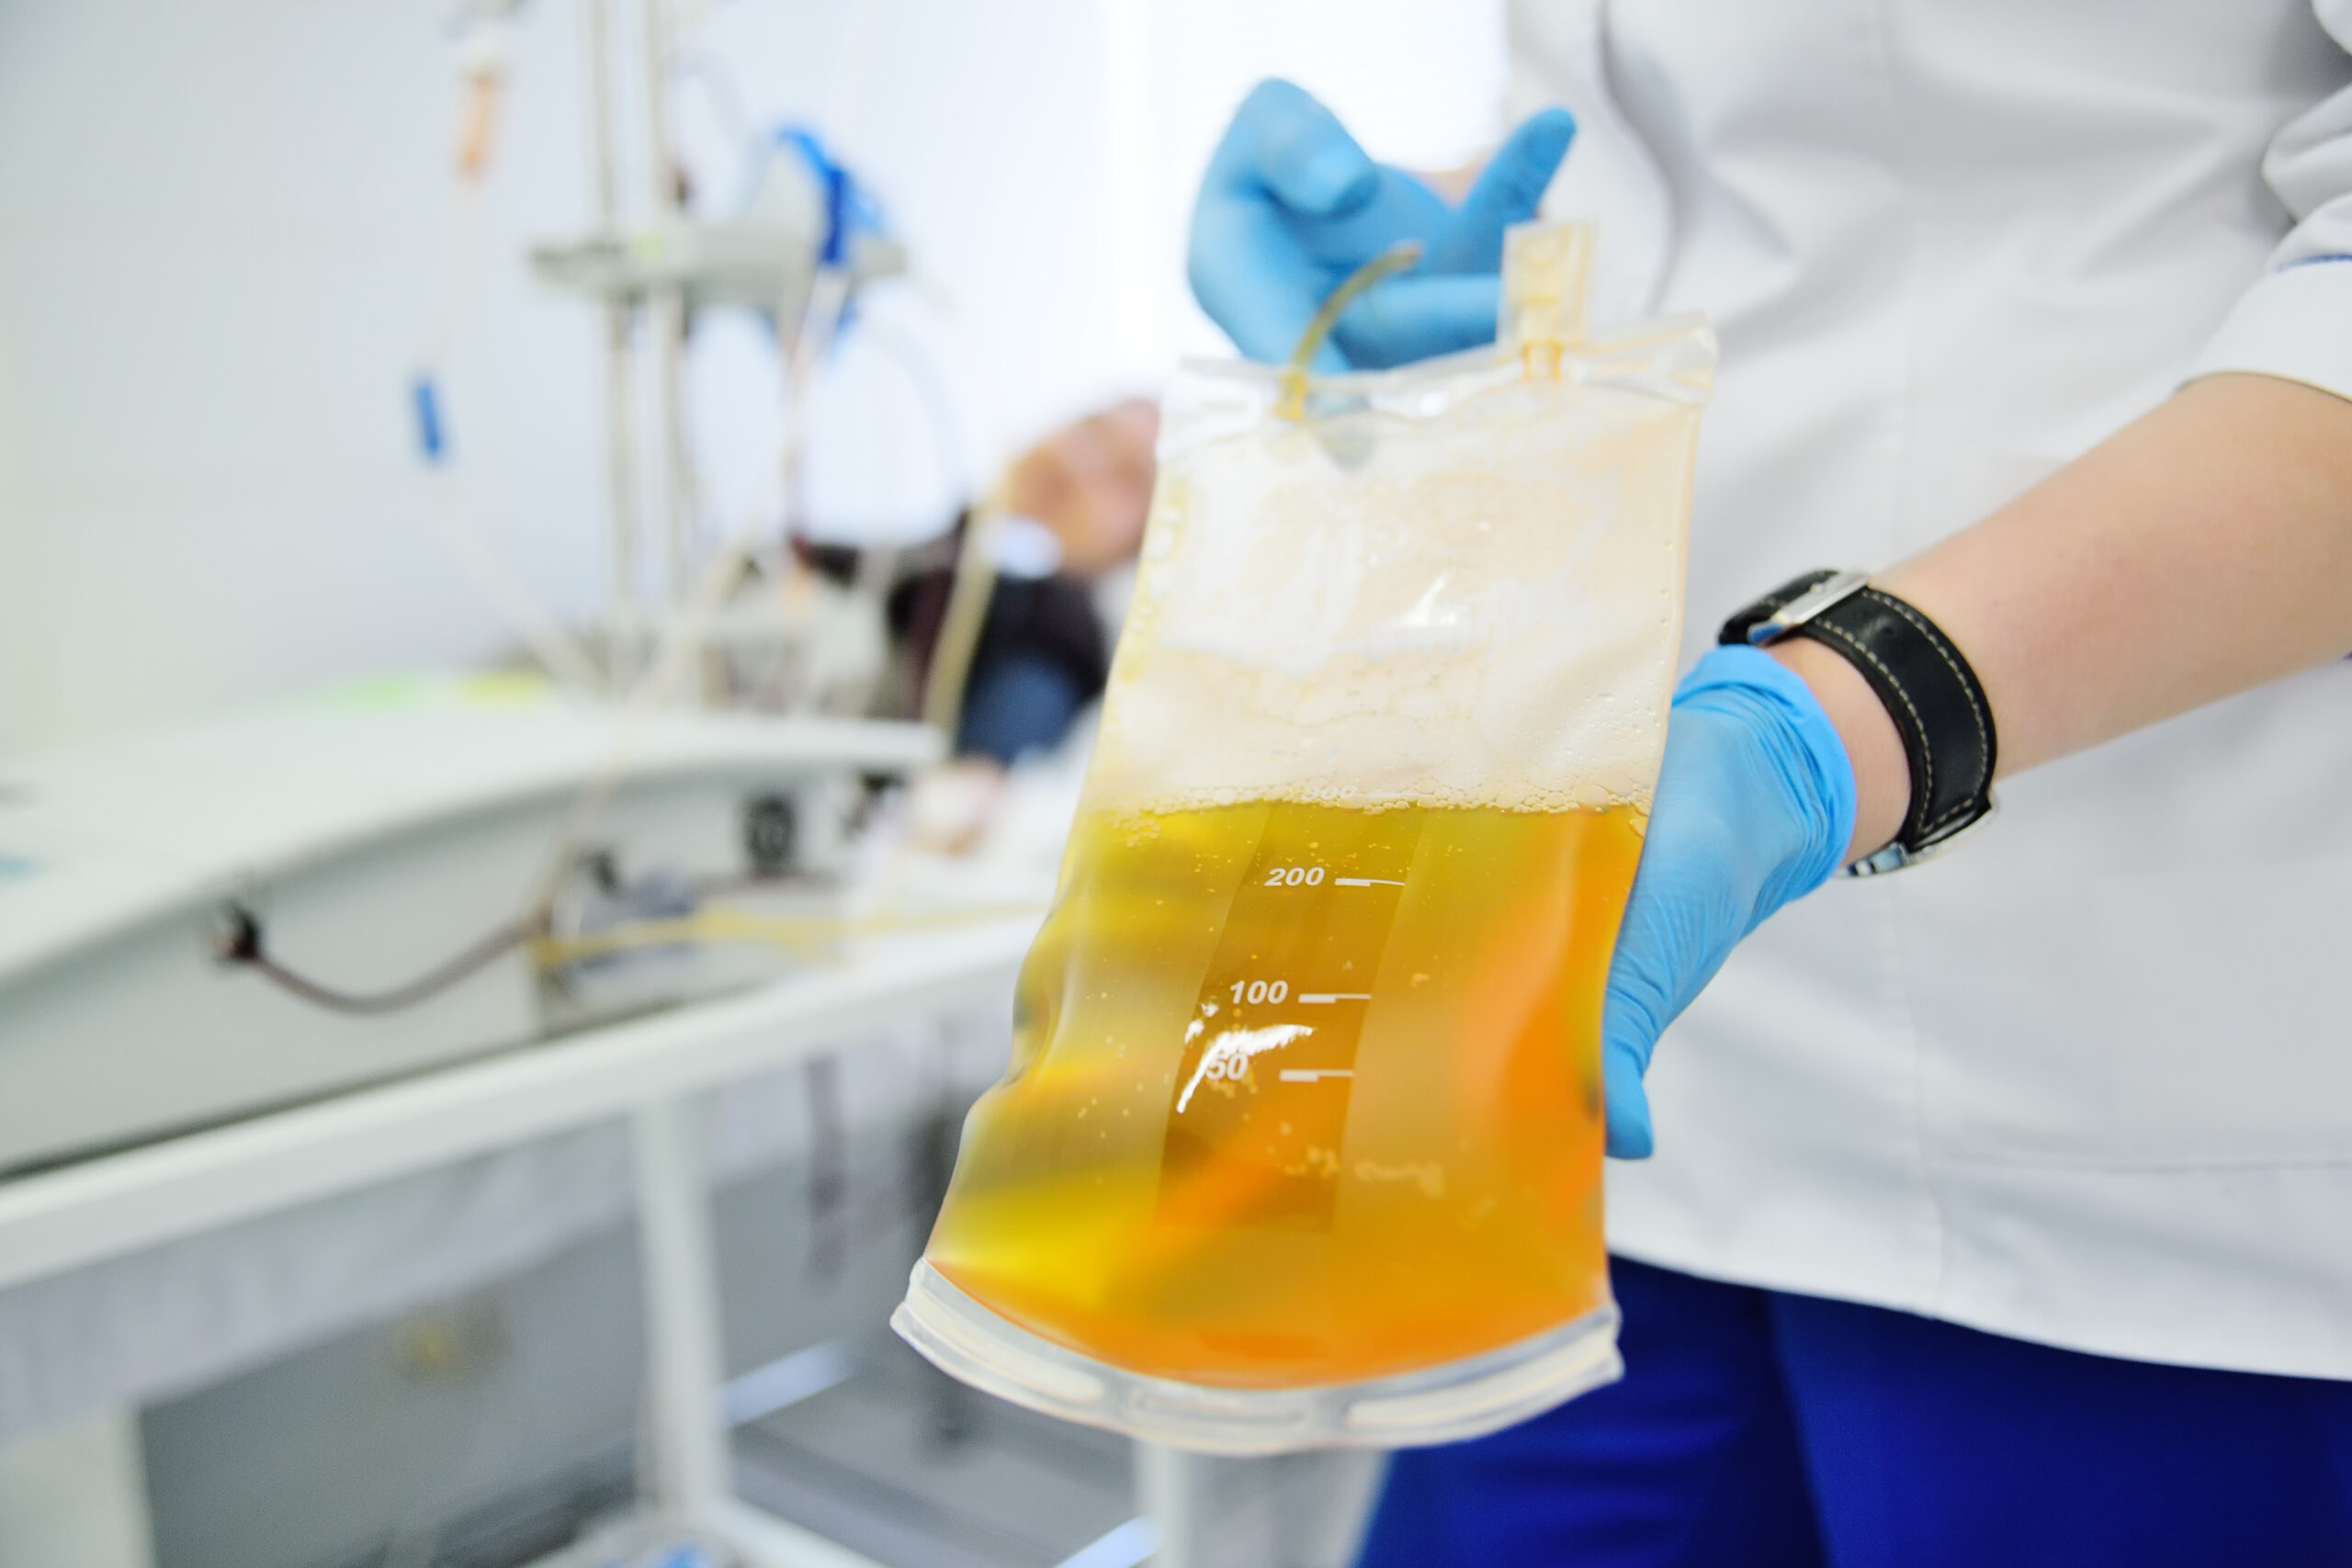
This growth is underpinned by the increasing necessity for immunoglobulins, coagulation factor concentrates, and albumin to treat complex immunological, neurological, and hematological conditions. As demand rises, industry leaders are prioritizing heavy investments in plasma collection infrastructure and advanced purification technologies. Major players like CSL, Takeda, and Grifols currently dominate a highly consolidated landscape, accounting for approximately 85-90% of the market.
North America maintains its position as the largest regional contributor, benefiting from sophisticated collection networks and established manufacturing capabilities. Recent strategic moves underscore this trajectory, including substantial capital injections—such as CSL’s $1.5 billion investment in U.S. manufacturing—aimed at fortifying supply chains. The sector is moving toward high-efficiency production methods, with therapeutic applications representing 95% of the market's current usage, signaling a long-term transition toward specialized, high-value medical treatments.


Comments (0)
No comments yet. Be the first!