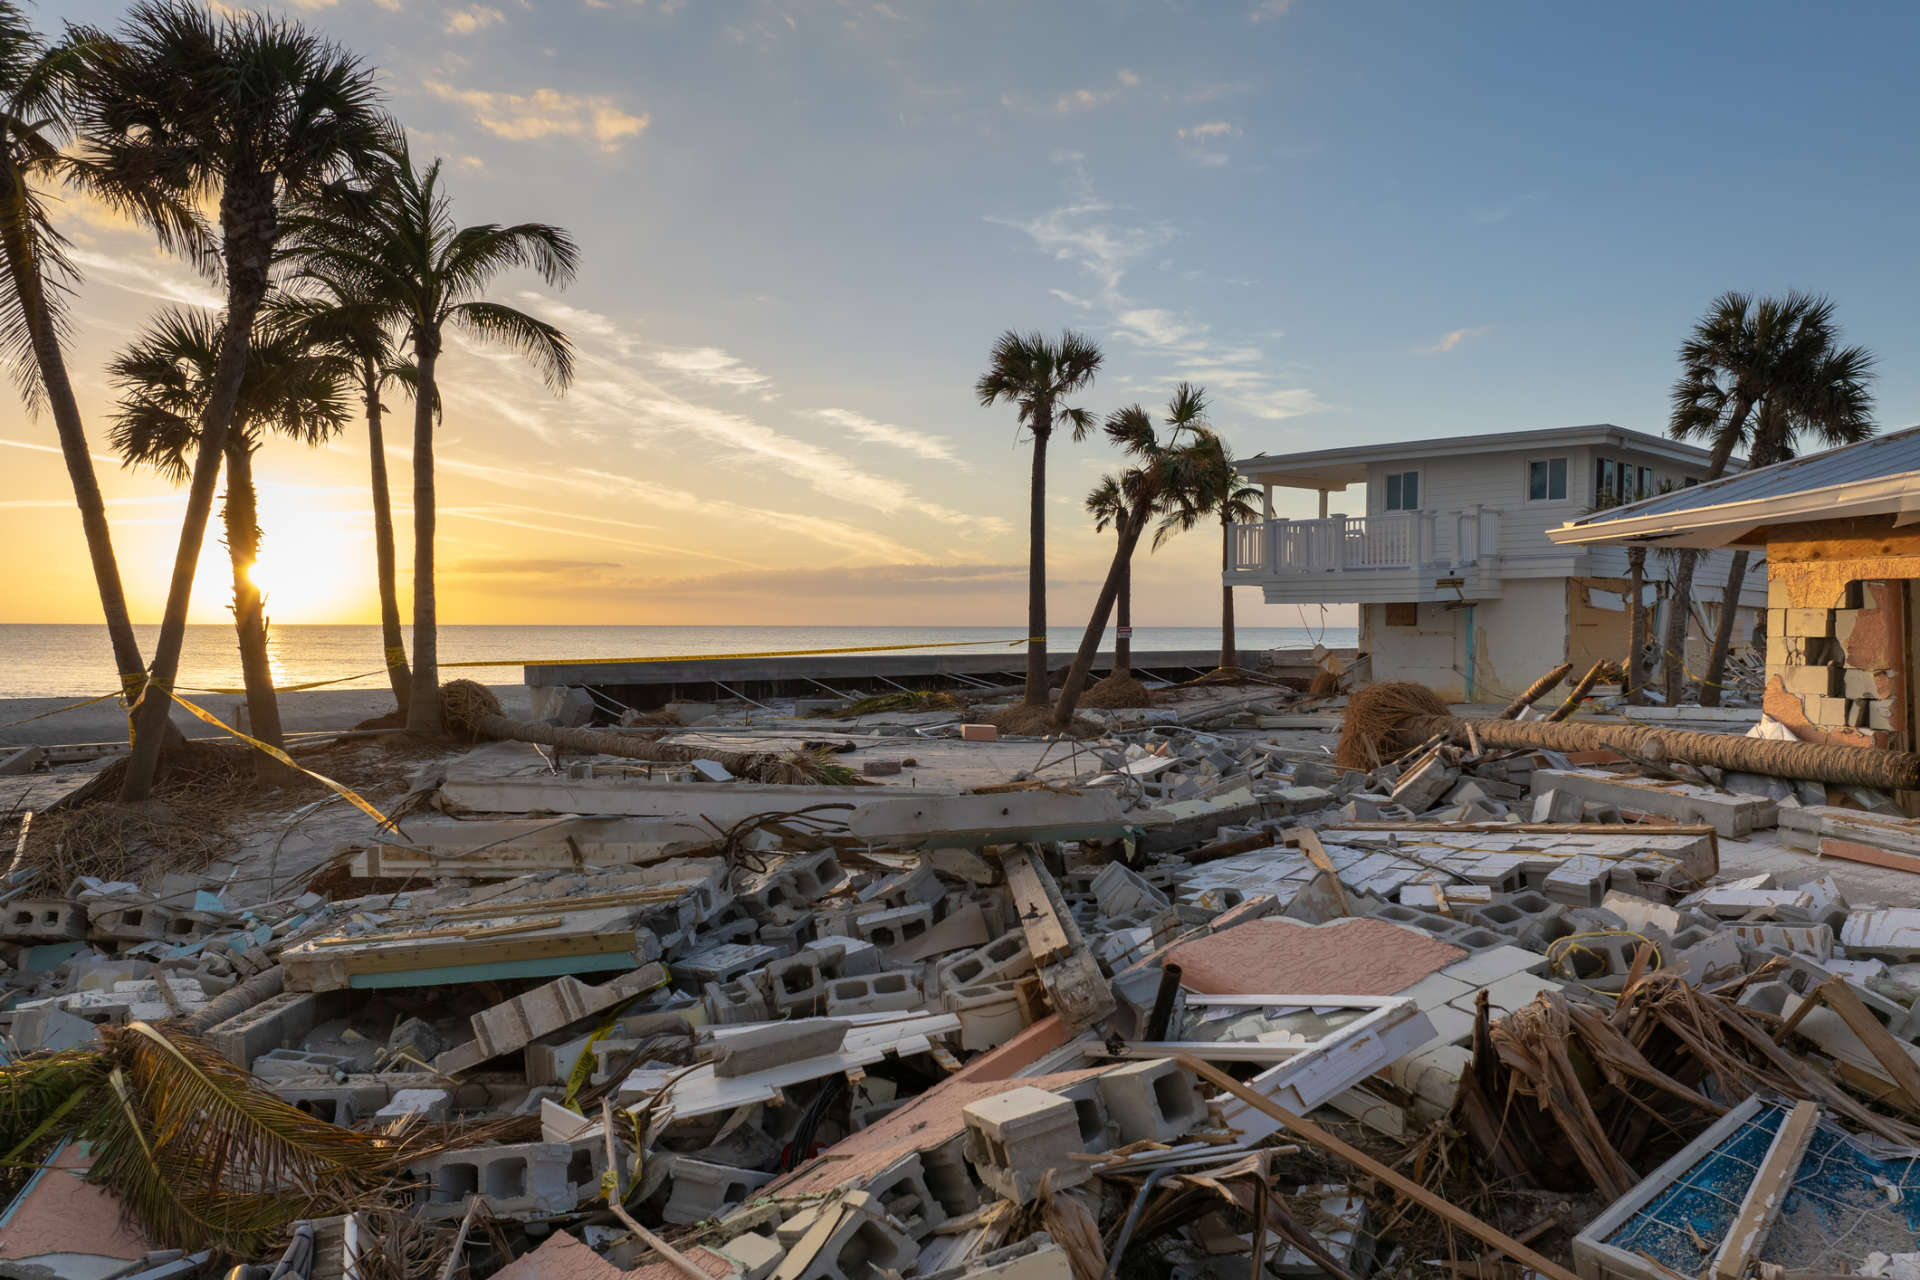
Harlingen-based insurance agent Doug Thompson highlights that this percentage-based structure forces homeowners to rethink their emergency budgeting. For instance, a two percent deductible on a home insured for two hundred thousand dollars results in a four thousand dollar out-of-pocket cost. In high-risk coastal zones, these percentages can climb higher, leaving owners exposed to substantial expenses before insurance coverage even kicks in.
Policyholders often have the flexibility to trade higher premiums for lower deductible percentages, but navigating these choices requires a clear understanding of local regulations. The Texas Department of Insurance enforces specific rules in high-risk areas, where windstorm coverage is sometimes separated from standard policies. Because these deductibles can apply to detached structures and garages as well as the main house, Thompson advises residents to audit their coverage annually. Proactive measures, such as installing storm shutters or reinforcing roofs, remain the most effective ways to mitigate risk and potentially influence insurance costs before the next hurricane season arrives.


Comments (0)
No comments yet. Be the first!